
Are You Keeping Employee Information Longer Than Necessary?
HR should establish retention and disposal practices to reduce data risks.

Understanding the ACA's 95% MEC offer requirement and monitoring it throughout the year can help employers avoid costly penalties.
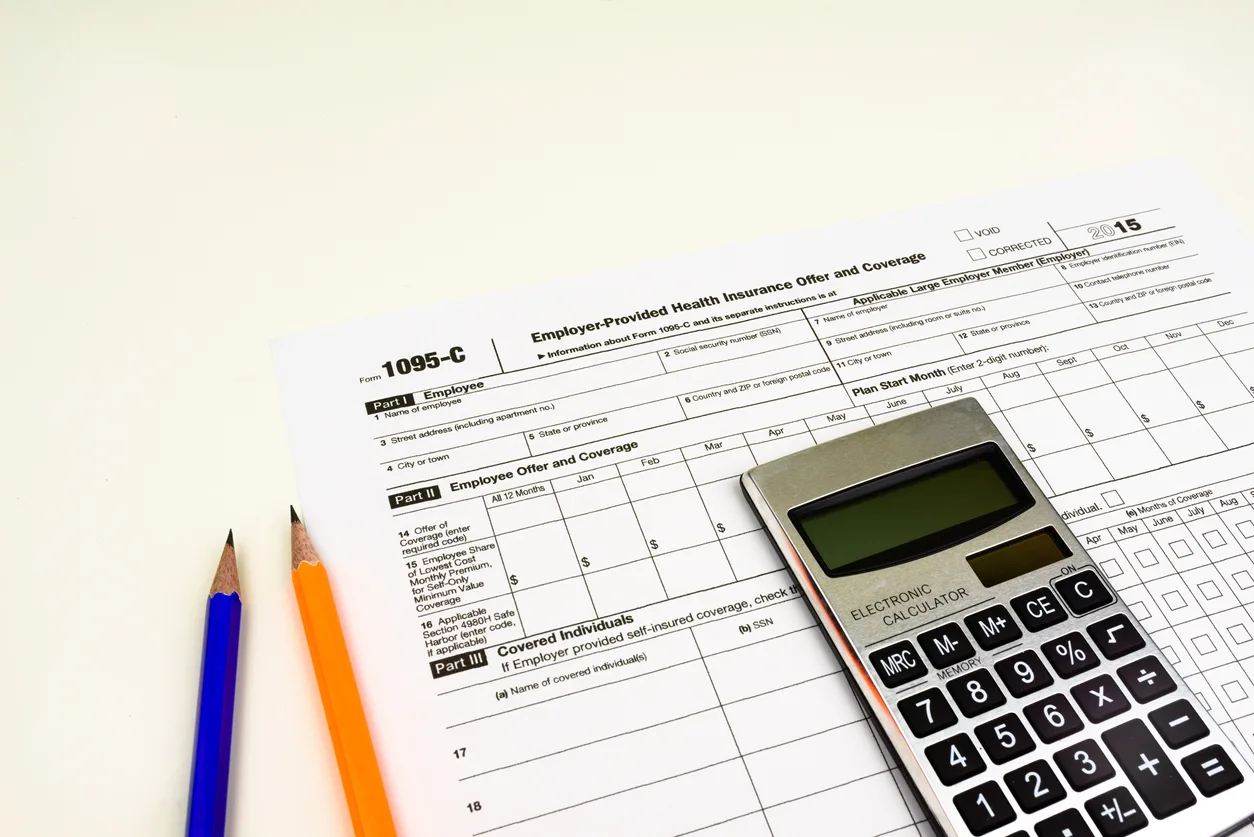
For applicable large employers (ALEs), complying with the Affordable Care Act (ACA) involves more than offering an affordable health insurance plan. Employers must also ensure that coverage is offered to a sufficient percentage of their full-time employees and their dependents. Even when an employer has a compliant health plan, administrative errors involving eligibility, enrollment, or employee records can create unexpected compliance risks.
Understanding the ACA’s 95% offer requirement and monitoring it throughout the year can help employers avoid costly penalties.
Under the ACA’s employer shared responsibility provisions, ALEs, generally employers with 50 or more full-time employees, including full-time equivalent employees, must offer minimum essential coverage (MEC) to at least 95% of their full-time employees and their dependents to avoid potential penalties under Section 4980H(a).
For this purpose, dependents generally include an employee’s children under age 26, but not spouses.
An ALE that fails to meet the 95% threshold for a month may face a significant employer shared responsibility penalty if at least one full-time employee receives a premium tax credit for coverage purchased through the Health Insurance Marketplace.
Importantly, the 95% requirement is based on offers of coverage, not employee enrollment. An employee who declines a valid offer of coverage generally still counts as having received an offer.
Employers may assume they are meeting the 95% requirement because they offer health insurance to all eligible employees. However, problems can arise when eligibility and enrollment processes do not accurately reflect employees’ employment status or coverage opportunities.
Common issues include:
These errors may affect only a small number of employees, but they can become significant when an employer is close to the 95% threshold.
The ACA allows a limited margin for employees who do not receive an offer of coverage. However, employers should not view this as permission to routinely overlook a portion of their workforce.
The threshold is determined monthly, and the consequences of falling below it can be substantial. If the applicable conditions for a Section 4980H(a) penalty are met, the assessment is generally based on the employer’s total number of full-time employees, subject to the applicable statutory reduction, rather than only the employees who did not receive offers.
This makes accurate eligibility administration especially important.
Employers should establish processes to monitor ACA eligibility and coverage offers throughout the year rather than waiting until annual reporting begins.
Recommended practices include:
ACA compliance requires ongoing monitoring, not just year-end reporting. Employers that use BAS for ACA data collection and reporting have access to a module that tracks whether the 95% offer-of-coverage requirement is being met throughout the year.
BAS sends reminders to employers to review their 95% offer-of-coverage status, providing an opportunity to identify potential gaps and take corrective action before they become larger compliance issues.
By monitoring coverage offers throughout the year rather than waiting until annual ACA reporting, employers can address eligibility and enrollment issues promptly and reduce the risk of costly penalties.
Benefit Allocation Systems (BAS) provides online solutions for: Employee Benefits Enrollment; COBRA; Flexible Spending Accounts (FSAs); Health Reimbursement Accounts (HRAs); Leave of Absence Premium Billing (LOA); Affordable Care Act Record Keeping, Compliance & IRS Reporting (ACA); Group Insurance Premium Billing; Property & Casualty Premium Billing; and Payroll Integration.
MyEnroll360 integrates with major insurance carriers for enrollment eligibility management (e.g., Blue Cross, Blue Shield, Aetna, United Health Care, Kaiser, CIGNA and others), and with leading payroll platforms for enrollment deduction management (e.g., Workday, ADP, Paylocity, PayCor, UKG, and others).
This article is for informational purposes only and is not intended as legal, tax, or benefits advice. Readers should not rely on this information for taking (or not taking) any action relating to employment, compliance, or benefits. Always consult with a qualified professional before making decisions based on this content.
HR should establish retention and disposal practices to reduce data risks.

Not every product or service that promotes health qualifies for tax-free reimbursement.
Using an outside service provider generally does not transfer legal responsibility for ACA compliance.